
Fetching the post and any attachments now.
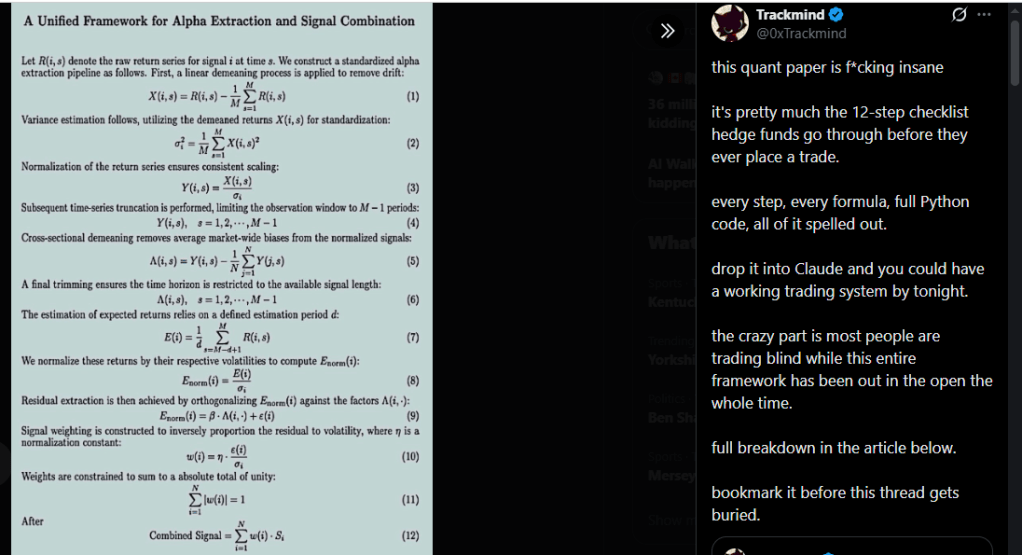
This is the 12-step quant pipeline from the image: a standardized alpha-extraction and signal-combination checklist. Correspondence, not identity. It sits on the fixed stations as a data-cleaning and weighting path. Headings stay. No new column. No claim it extracts non-scalar residual in the Ace sense.
Twelve stations. Quant signal checklist as marks.
| I | II | III | IV | V | VI | VII | VIII | IX | X | XI | XII |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Arena | Path | Compare | Small loop | Holonomy | Residual | Mean tide waits | Closure test | Toggle +/− | Store sector | Read face | Growth face μ |
| raw return series (R(i,s)) | linear demeaning X=R−Rˉ | variance against the series | one normalization | truncated window still full | cross-sectional demean Λ=Y−Y | volume of expected return not yet the law | estimation period d; | Enorm kept or residualized | residual orthogonalized against factors | weights ⋅ϵ(i)/σi clamped to $$\sum | w |
Read left to right. You do not begin with a trade. You begin with the raw series. You remove drift. You estimate variance. You normalize once. You keep the truncated series. You demean cross-sectionally so the residual is not the market. You do not open a volume law of expected return before the window is set. You estimate. You toggle: normalize further or extract the residual by orthogonalization. You store the residual. You read the inverse-vol weights and clamp them. You let the growth face form the combined signal.
It fits as a control reading of the same twelve headings. Equation (9) is the residual extraction; equation (10)–(11) is the clamp. The machine can retrieve the pipeline. The man chooses whether the factors in the orthogonalization hide a parent. No ripple claimed. No Project 6 solved. Scalar reweighting inside a fixed window is still a scalar gate.

